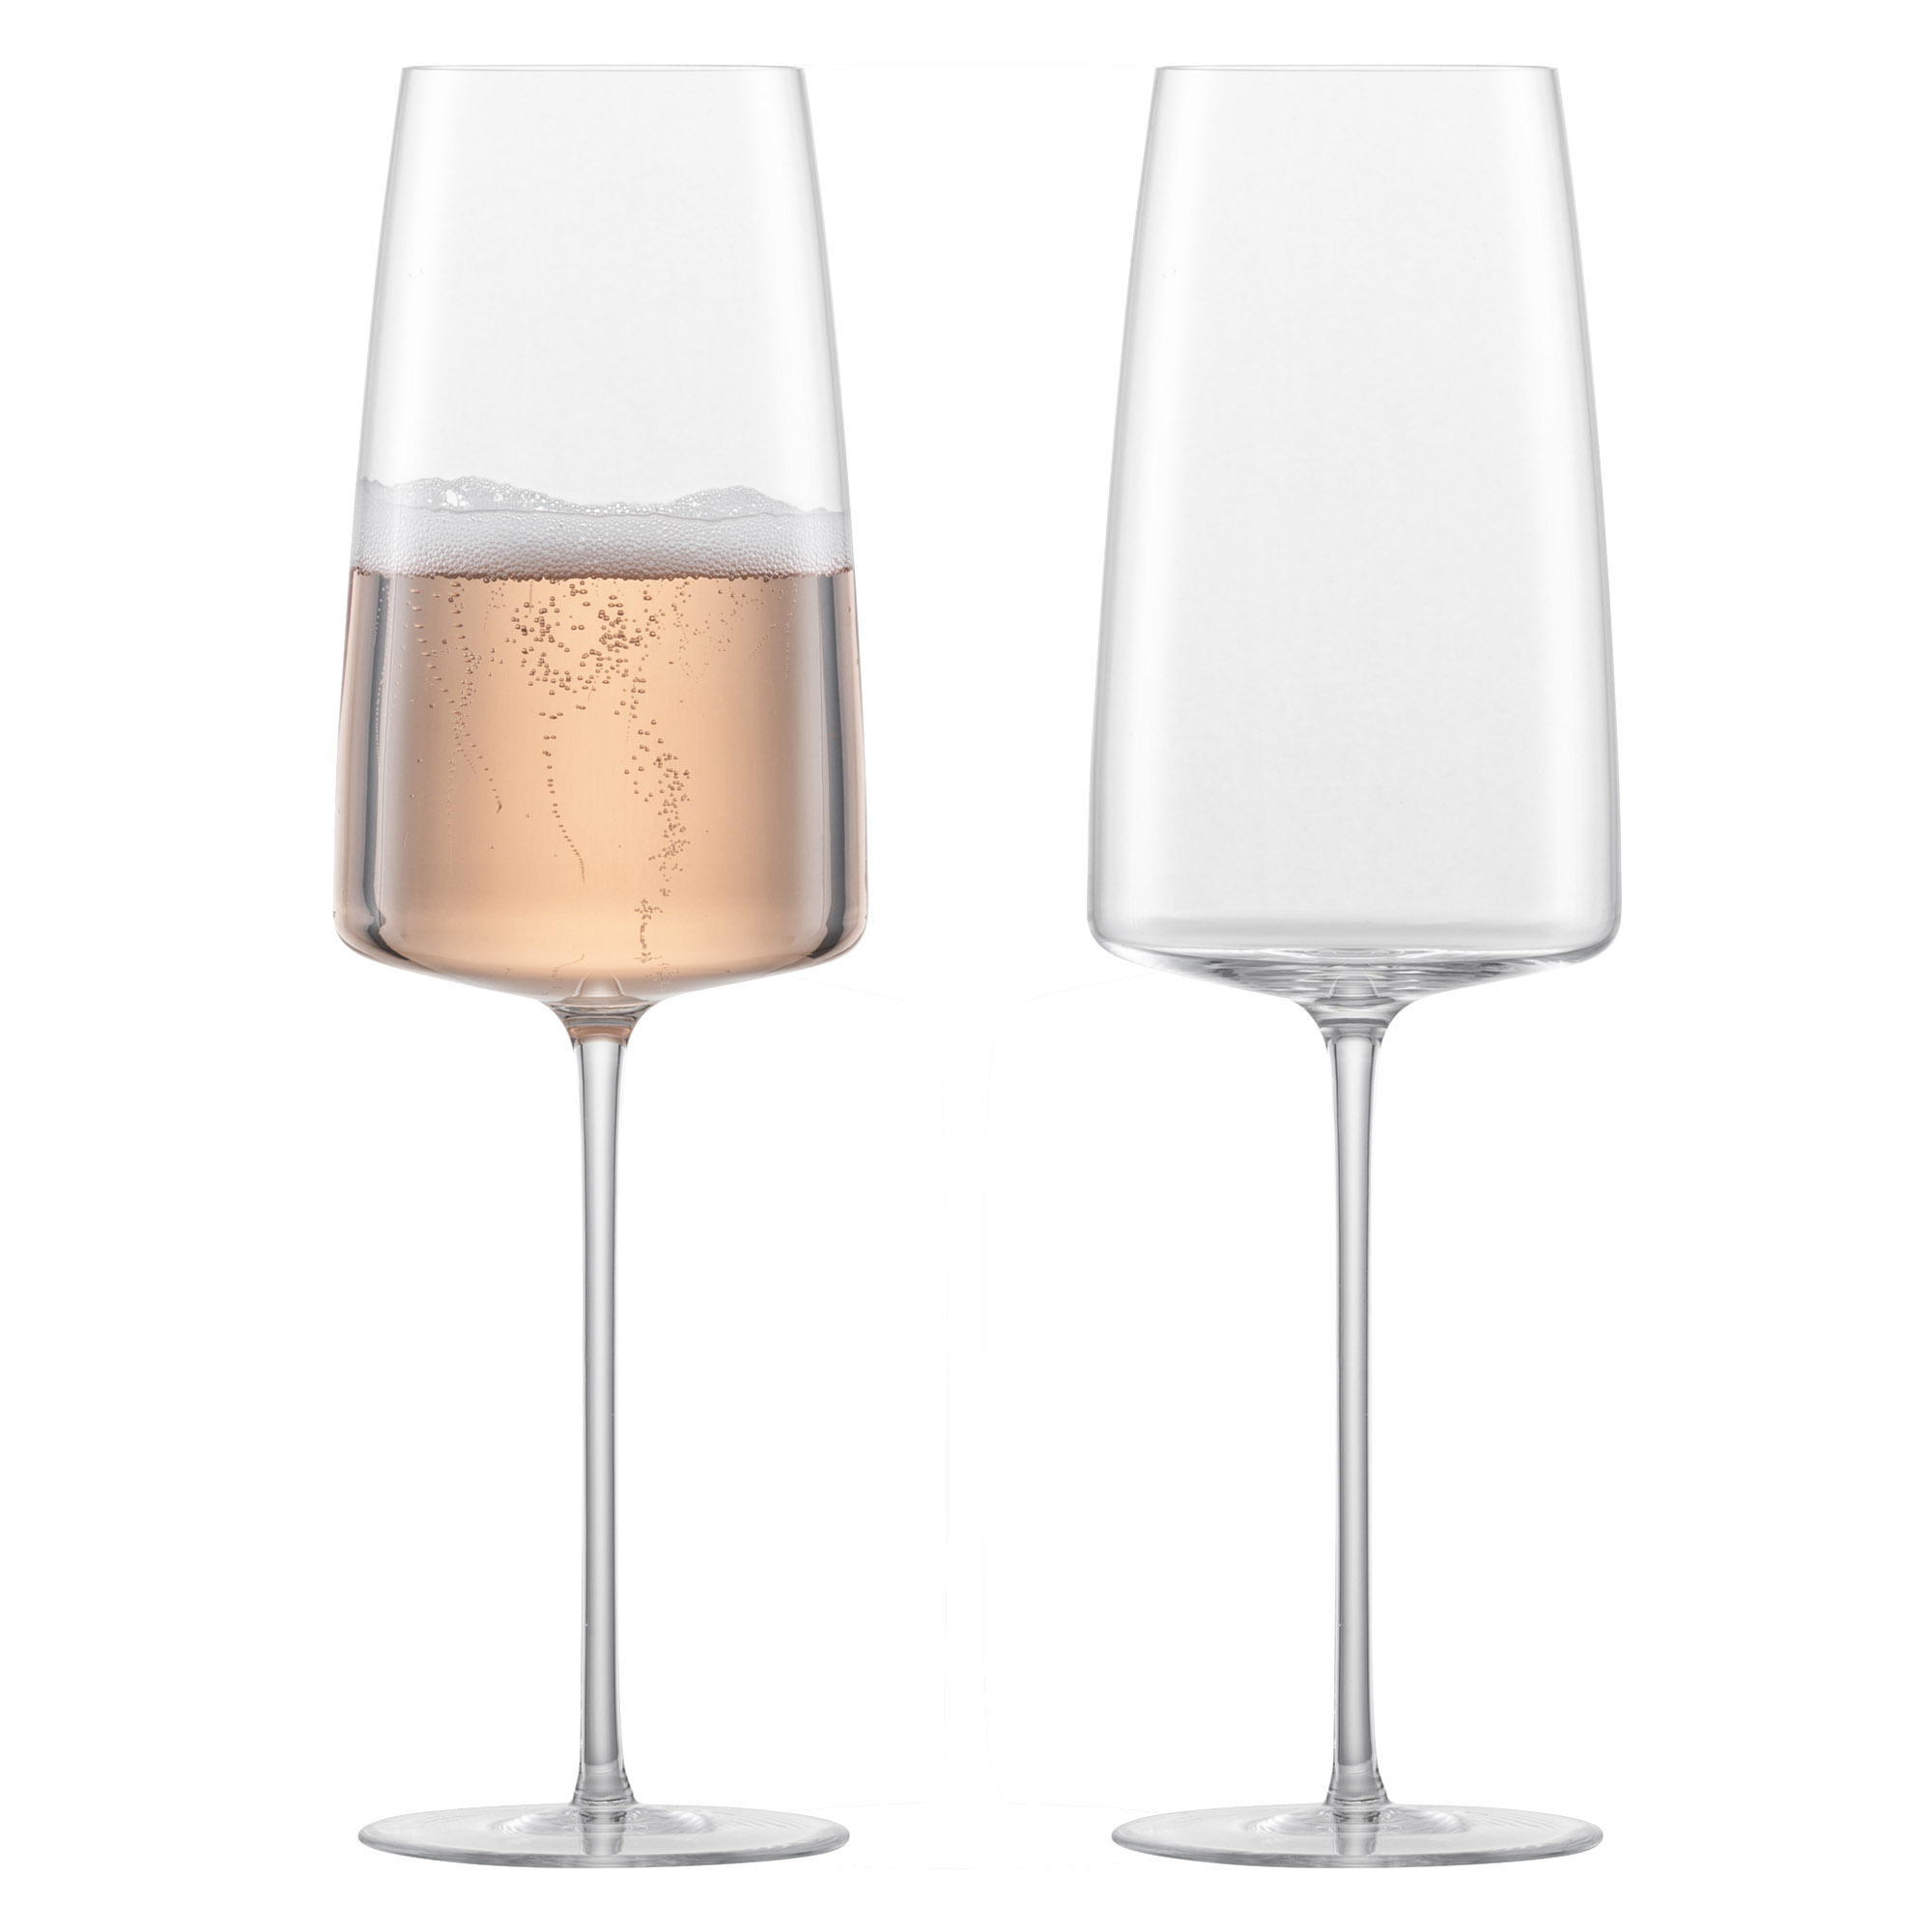
sektgläser ohne stiel ZWIESEL GLAS Serie SIMPLIFY Sektglas leicht & frisch mundgeblasen 2 Stück 407 ml Corto sektgläser
EUR28.11
EUR66.11
Pay in 4 interest-free payments of $7.03 Learn more
Shipping Estimate
USA
- USA
- CAN
- USA
- CAN
Ships within 48 hours · Estimated delivery Oct 24 - Oct 29
Hall notes
Description
sektgläser ohne stiel ZWIESEL GLAS Serie SIMPLIFY Sektglas leicht & frisch mundgeblasen 2 Stück 407 ml Corto sektgläser
SOLID Dessertteller beige, Ø 21,5 cm | Moritz & Moritz
Ob als Geschenk zur Verlobung, Hochzeit, zum Jahrestag oder einfach als liebevolle Aufmerksamkeit zwischendurch – diese Thermobecher sind mehr als nur praktische Alltagshelfer: Sie sind ein Symbol für Partnerschaft, Liebe und gemeinsame Momente
rechteckig
Motiv:Metatron Gold
Die originellen Weingläser aus bleifreiem Kristallglas aus Nový Bor zeichnen sich durch einen einzigartig spiralförmig gestalteten Kelch aus, der den Wein beim Schwenken natürlich belüftet und so hilft, sein volles Aroma und seinen Geschmack sofort freizusetzen
Exchange/Return Notes
- We offer a 30-day return/exchange service after receiving.
- Final sale items are not eligible for returns or exchanges.
- To process your return/exchange, please contact us at [email protected]
- Please click here for more details>>> Return & Exchange Policy
Frequently Asked Questions for sektgläser ohne stiel ZWIESEL GLAS Serie SIMPLIFY Sektglas leicht & frisch mundgeblasen 2 Stück 407 ml Corto sektgläser
What should I compare before choosing a bundle instead of individual options?
Check whether all components are available under the same fulfillment arrangement. Check whether a customization choice changes the bundle contents.
What should I record if a purchase-related problem happens only sometimes?
Record the relevant date without inventing an exact frequency. Record changes to the arrangement that might provide useful context.
What should I confirm before purchasing on behalf of an organization?
Do not assume an ordinary buyer account automatically represents an organization. Review whether the selected offer permits the planned organizational use.